The Tokenisation Market Is Bigger Than Its Infrastructure
A panel at the Global WealthTech Summit in London argued that private markets do not primarily need more tokens. They need an operating model that can handle ownership, valuation, custody, settlement and liquidity — without adding another fragmented layer to existing infrastructure.

Tokenisation has moved from a crypto-adjacent experiment to a mainstream wealth-management agenda item. Asset managers, private banks, custodians and fund administrators are all being asked the same question: which assets should be tokenised, and when?
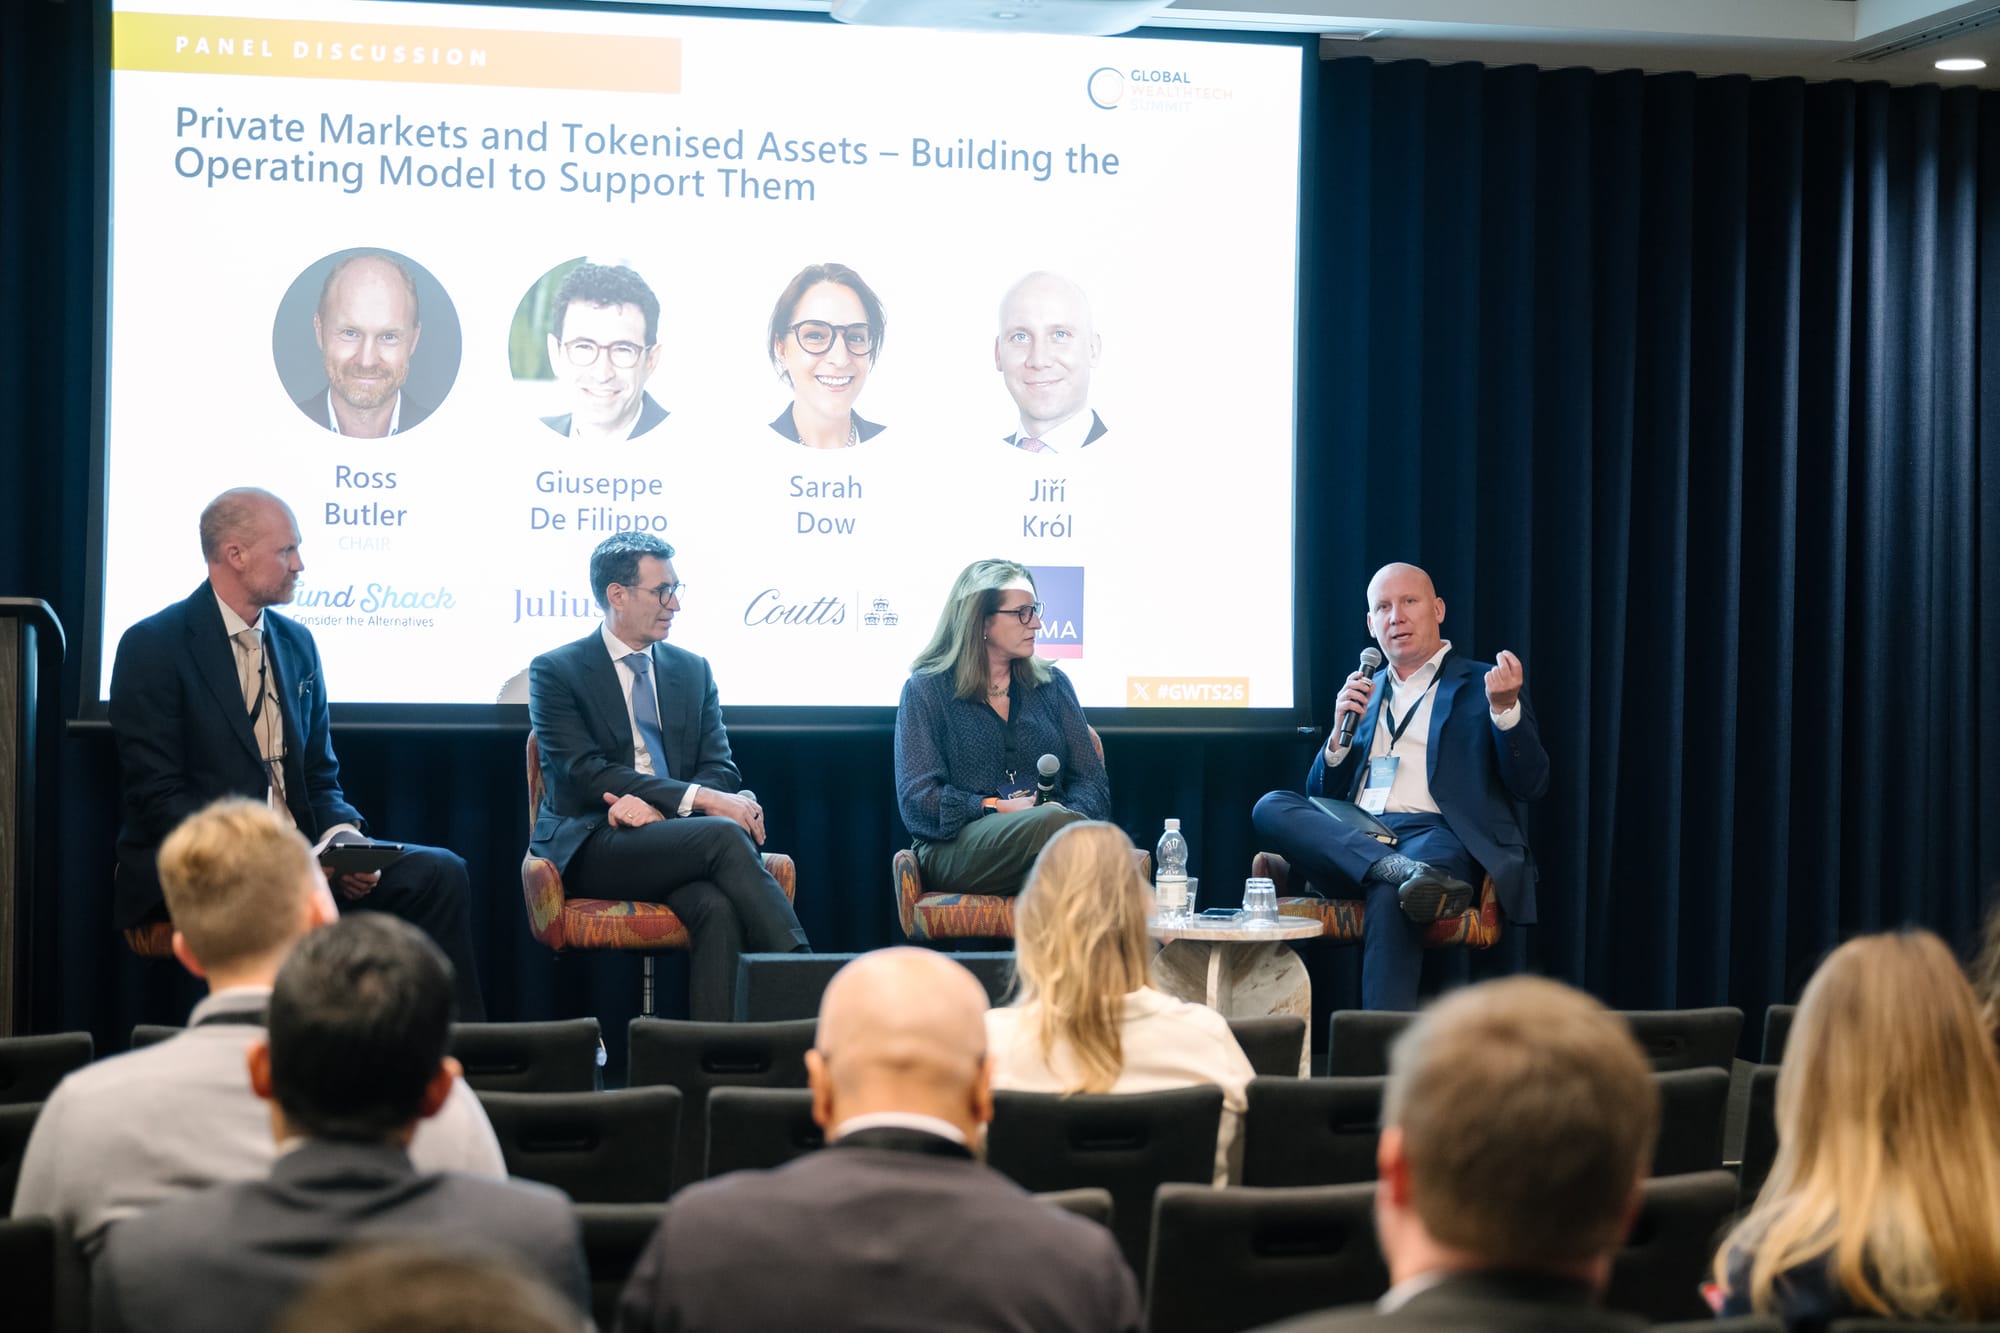
At the Global WealthTech Summit in London, the panel “Private Markets and Tokenised Assets – Building the Operating Model to Support Them” offered a more disciplined answer.
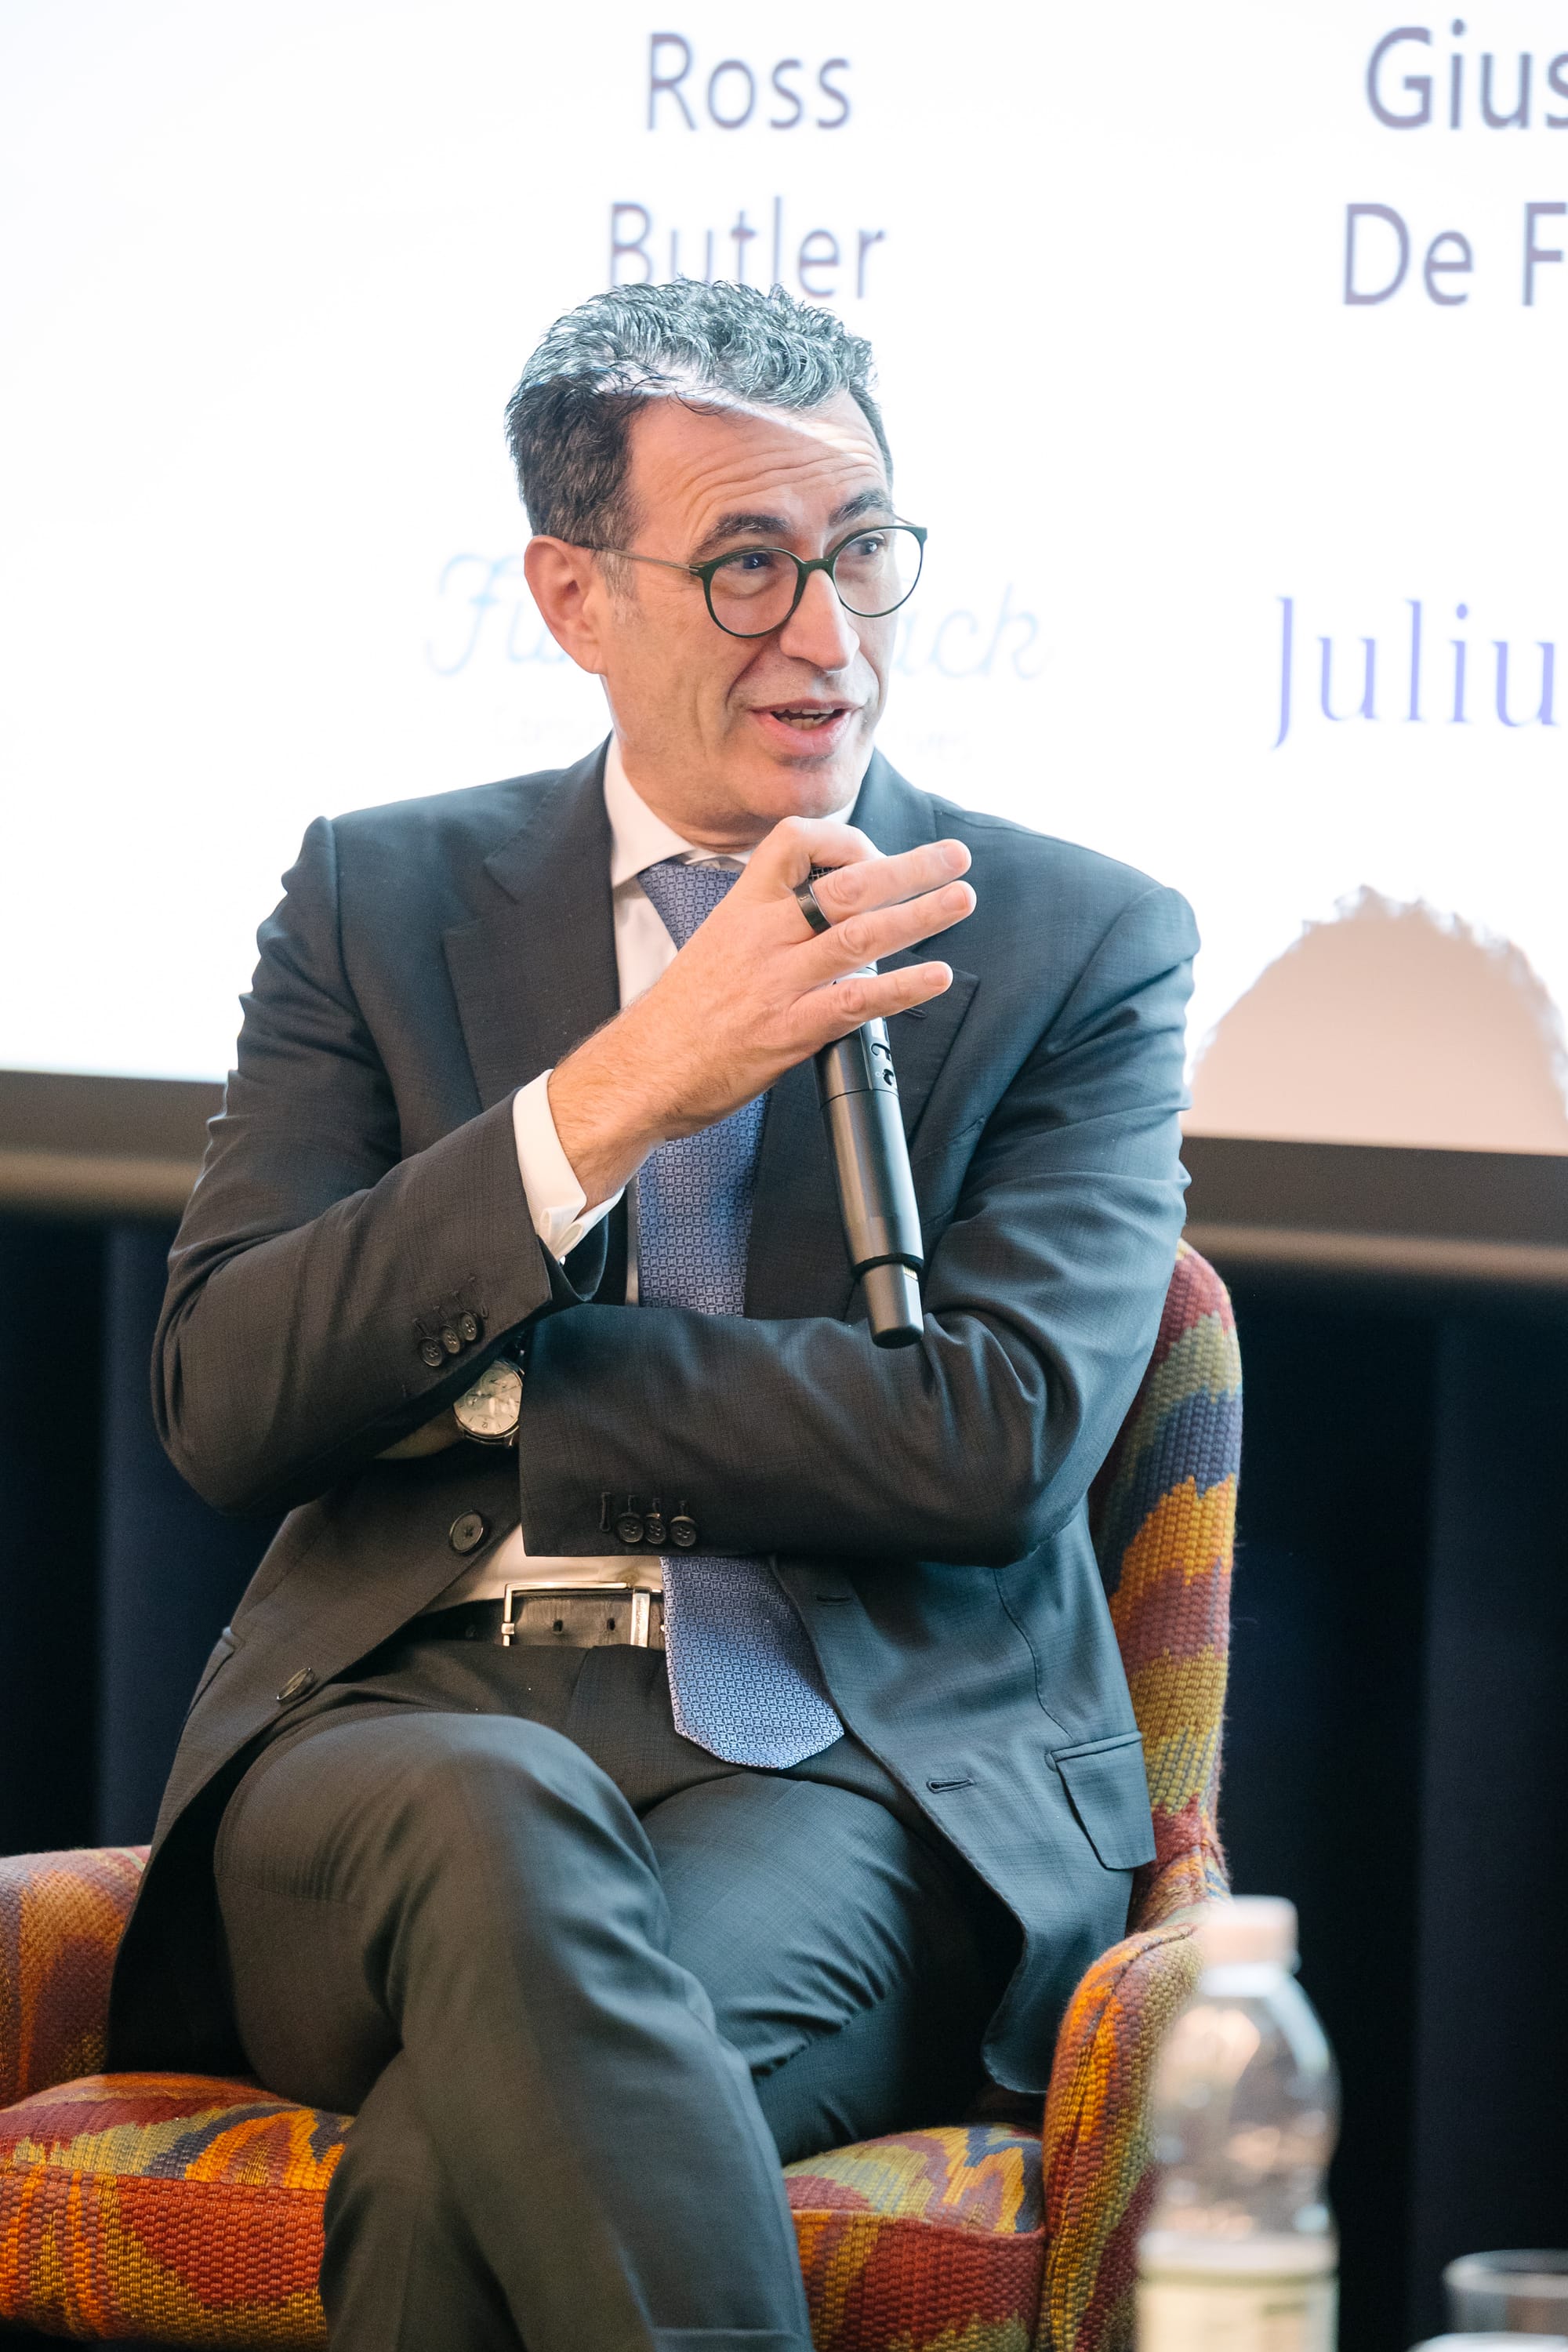
Moderated by Ross Butler, Founder and Host of Fund Shack, the session featured Giuseppe De Filippo, Managing Director and Head of Private Capital Markets at Julius Baer; Sarah Dow, Head of Digital Asset Strategy and Delivery at Coutts; and Jiří Król, Deputy CEO of AIMA.
Their conclusion was not that tokenisation lacks potential. It is that the market is being measured by the wrong metric.
A $350 Billion Market, But a Shallow One
The panel referenced research putting the tokenised-asset market at roughly $350–360 billion. But the more important number was what sits beneath that headline.
According to the discussion, only around 1% of tokenised private assets are truly native to a blockchain — issued, held and transferred on the ledger itself. The rest largely function as digital representations of assets that remain recorded and controlled in traditional systems.
That assessment is broadly consistent with Pantera Capital’s State of Tokenization research, which analysed 593 tokenised assets across 11 asset classes representing roughly $321 billion in tracked market value. Pantera found that 77.6% of scored assets fell into its “Wrapper” tier, 11.1% were “Hybrid,” and only 2.7% reached the “Native” tier. The average Tokenization Progress Index score was 2.04 out of 5.
In other words, the market has proven that assets can be represented on-chain. It has not yet proven that on-chain representation fundamentally changes how most assets are issued, transferred, valued or serviced.
A Token Is Not Automatically Ownership
One of the sharpest points in the discussion concerned legal ownership.
A token may represent an asset, but that does not necessarily mean it confers ownership in a legal sense. In some structures, the token is closer to a record or receipt: it points to an interest held elsewhere, often with a custodian, administrator or company registry.
This matters especially in private markets.
A private-market fund interest may appear on an investor’s bank statement, but the underlying LP interest is typically held and administered by the fund administrator. Similarly, a private-company share is not owned simply because someone has bought a claim to it; ownership depends on the company’s share registry, transfer consents and any rights of first refusal.
The panel referenced cases involving private-company shares traded on secondary platforms where the underlying companies subsequently indicated that the transfers were not valid. The broader lesson is that a secondary transaction in a private asset does not automatically create a legally effective transfer of ownership.
Tokenisation does not remove those constraints by default. A token can only become the authoritative ownership record if the asset is issued natively on the ledger and the relevant legal, regulatory and corporate-governance framework supports it.
Liquidity Is Not a Feature You Can Tokenise
The panel was unequivocal on one of tokenisation’s most persistent promises: liquidity.
A tokenised illiquid asset remains illiquid. Tokenisation does not create buyers, credible price discovery or sustained secondary-market demand.
The panellists noted that even in digital-asset markets — where assets are tokenised by definition — liquidity is uneven and often shallow. The issue is not whether an asset can be represented on a blockchain; it is whether there are participants willing to buy and sell it at transparent prices, in meaningful size.
For private markets, liquidity still comes from familiar sources:
- Redemption windows and fund-level liquidity terms.
- Secondary markets, where market makers or banks are willing to provide pricing.
- Credit facilities or other financing structures.
- Genuine investor demand for exit.
Tokenisation may make the administration of those mechanisms more efficient. It may reduce manual steps in transfer, reporting or investor servicing. But it does not replace the economic conditions required for liquidity.
The panel drew a useful distinction between economic liquidity — an investor’s ability to get money back — and technical liquidity, meaning the ability to move or transfer a digital representation of an asset. Tokenisation can improve the latter without necessarily improving the former.
The Near-Term Opportunity Is Back Office
If tokenisation is unlikely to solve private markets’ liquidity problem in the short term, where is its practical value?
The panel’s answer was operational rather than speculative.
The most credible near-term use cases sit in the back office:
- Faster and cheaper settlement, particularly where traditional processes can take several days depending on asset type and transaction size.
- Client onboarding once across multiple funds or products, rather than repeating fragmented subscription and KYC processes.
- Better data management for complex assets, including maintenance records, valuations, certifications and other reference data.
- More scalable servicing of evergreen funds, which can involve large numbers of smaller subscriptions and periodic redemption requests.
This is particularly relevant as private markets broaden beyond institutional committed-capital structures. Traditional private-market funds were designed around a small number of large institutional subscriptions. Evergreen funds, private credit and wider wealth-management distribution create a different challenge: many more investors, more frequent transactions and greater demand for standardised workflows.
Tokenisation can help with that — but only if it is implemented as part of a coherent operating model rather than as an isolated technology project.
Interoperability Is the Real Bottleneck
Even where tokenisation makes sense, the panel identified a larger barrier: coordination.
A tokenised fund involves more than an asset manager. It typically requires alignment between the custodian, administrator, distributor, transfer agent and technology provider. If each participant uses different standards, workflows or ledgers, tokenisation can create additional fragmentation rather than reduce it.
The panel compared the challenge to payments. SWIFT works because the industry broadly agrees on how banks exchange payment information. Tokenised assets still lack an equivalent shared interoperability layer at scale.
Recent experiments suggest progress. The panel cited Singapore’s sandbox testing, including a demonstration in which a deposit token moved between four banks through a basic interoperability layer. But such tests remain early relative to the coordination required across global wealth-management ecosystems.
Without shared standards, a tokenised deposit or fund may still require a manual payment or reconciliation leg — undermining much of the intended efficiency gain.
Where Firms Should Start
The panel resisted giving a generic answer on where wealth managers should begin. The advice was to start with client data, client needs and existing operational friction.
That means asking practical questions:
- Which client segments want access to private markets but struggle with onboarding, reporting or liquidity terms?
- Which products generate the highest volume of manual subscriptions, transfers or reconciliations?
- Where would better data or faster settlement create measurable value?
- Which assets have sufficiently standardised ownership, pricing and servicing processes to justify tokenisation?
The suggested sequence was pragmatic: begin with cash, money-market instruments, credit and bonds, where ownership and pricing are more standardised. Private-market funds are more complex. Direct ownership of private companies is harder still, given transfer restrictions, negotiated valuations, limited price transparency and consent requirements.
Measure Function, Not Headlines
Tokenisation is no longer primarily a question of whether assets can be represented on a blockchain. In many cases, they can.
The more important question is whether doing so changes anything material:
- Does it improve settlement?
- Does it reduce reconciliation?
- Does it create a single, reliable client view?
- Does it improve valuation data?
- Does it make servicing scalable?
- Does it genuinely change ownership rights — or merely represent them differently?
If the answer to most of those questions is no, tokenisation risks becoming another layer of technology around an unchanged process.
The panel’s message was not that tokenisation lacks potential. It is that the industry should stop measuring progress by the value of assets described as tokenised, and start measuring it by the share of assets that are genuinely native, interoperable and operationally useful.
On that measure, the market is still early.
And for private markets, the hardest work — custody, valuation, ownership, liquidity and interoperability — remains ahead.